Netflix Beats on Profit, Then Slides After Hours as It Trims Its Ad Forecast and Guides Lower
A record 34.6 percent operating margin and a $4.8 billion buyback were not enough: weaker fourth-quarter guidance and a lower ad target sent the stock down about 5 percent after the bell.
Wednesday, October 21, 2026/2 min read
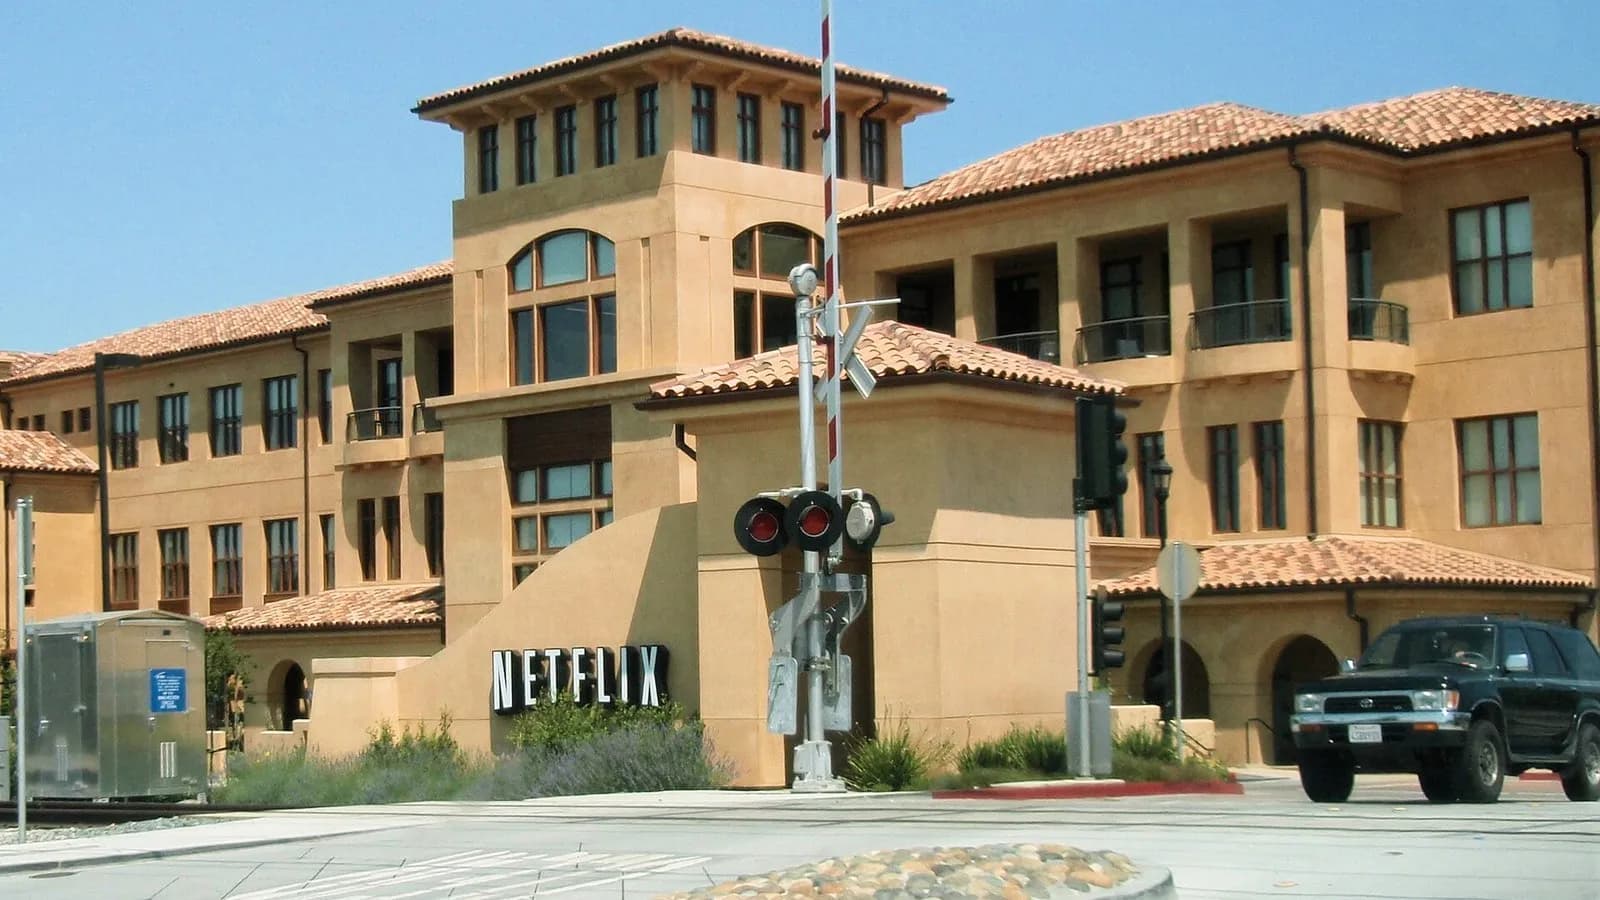
Netflix did the hard part and was punished anyway. The streamer reported third-quarter revenue of $12.87 billion, up 12 percent, and an operating margin of 34.6 percent, up from 28.2 percent a year earlier, according to its shareholder letter filed on Tuesday. Diluted earnings per share were $0.87, against $0.59 a year ago.
Shares fell about 5 percent after the close, from a $68.70 finish, FXStreet reported. The reason sits in the outlook, not the quarter.
What did Netflix report for the third quarter?
Revenue was in line with the company's own forecast. Operating income reached $4.5 billion, up 37 percent, and beat guidance mainly because of the timing of expenses. EPS of $0.87 topped the roughly $0.82 analysts expected, according to TradingKey.
Netflix also spent heavily on its own stock. It repurchased 63.9 million shares for $4.8 billion, its largest quarter of buybacks ever, and has $22.3 billion left under its authorisations. The letter said churn improved year over year, both globally and in the United States.
Why did the stock fall?
Guidance. For the fourth quarter Netflix forecast revenue of $13.4 billion, up 12 percent, but an operating margin of 26 percent and EPS of $0.67. TradingKey put the analyst consensus at $13.52 billion in revenue and $0.73 in EPS. About 120 basis points of the margin hit comes from the recently announced headcount reductions, the letter said.
Advertising is the second problem. TradingKey reported that Netflix cut its 2026 ad revenue forecast from about $3 billion to $2.7 billion, citing a slower-than-planned rollout of some ad product features. For a company that has leaned on its ad tier to keep growth up, that is the number investors read twice.
What about the layoffs?
Co-CEOs Greg Peters and Ted Sarandos told staff on 14 October that about 6 percent of the workforce, nearly 1,000 jobs, would go, with product, technology, legal and human resources hit hardest, the Associated Press reported. The cuts were the biggest at Netflix in years. Netflix had also agreed late last year to buy Warner's studio and streaming business, then walked away in February, and Paramount's takeover of Warner Bros. Discovery has since closed, AP noted.
The shareholder letter does not mention Warner. It describes selective M&A as one use of cash among several.
What to watch next
With the shares down nearly 27 percent for the year, according to TradingKey, Netflix now has to show that a 26 percent fourth-quarter margin is a one-off cost of restructuring and not a sign that growth has become more expensive. The first test is the next batch of ad-tier data, and the second is whether the buyback keeps running at this pace when the stock is cheaper.
Published in The Outspoken Digest
Editorial desk
Outspoken Digest Markets DeskReports for The Outspoken Digest across Business, Crypto.
Newsletter
The Digest, in your inbox
One edition, sent when it is ready. No noise, and your address is never passed on.
Read Next
More Business →
Jio Platforms Raises Rs 8,110 Crore From Anchors at the Top of Its Range as India's Biggest IPO Opens
Oct 21, 2026/2 min read
Wall Street Rebounds as AI Stocks Recover, With the Nasdaq Up 1.1% and the 10-Year Yield Above 5.15%
Oct 20, 2026/2 min read

CoreWeave Shares Fall 25 Percent in a Week as Its Bonds Flash Warning Signs for AI's Borrowers
Oct 18, 2026/2 min read
Nasdaq Ends Its Worst Week Since June as Chip Stocks Slide and Oil Climbs Toward $110
Oct 18, 2026/2 min read