The Dollar's Next Move Depends on Which Inflation Shock Lasts Longer
The Fed and ECB are both cautious, but their economies absorb the energy shock differently. Jobs, inflation and credit conditions will decide whether the policy gap widens.
Sunday, August 2, 2026/2 min read
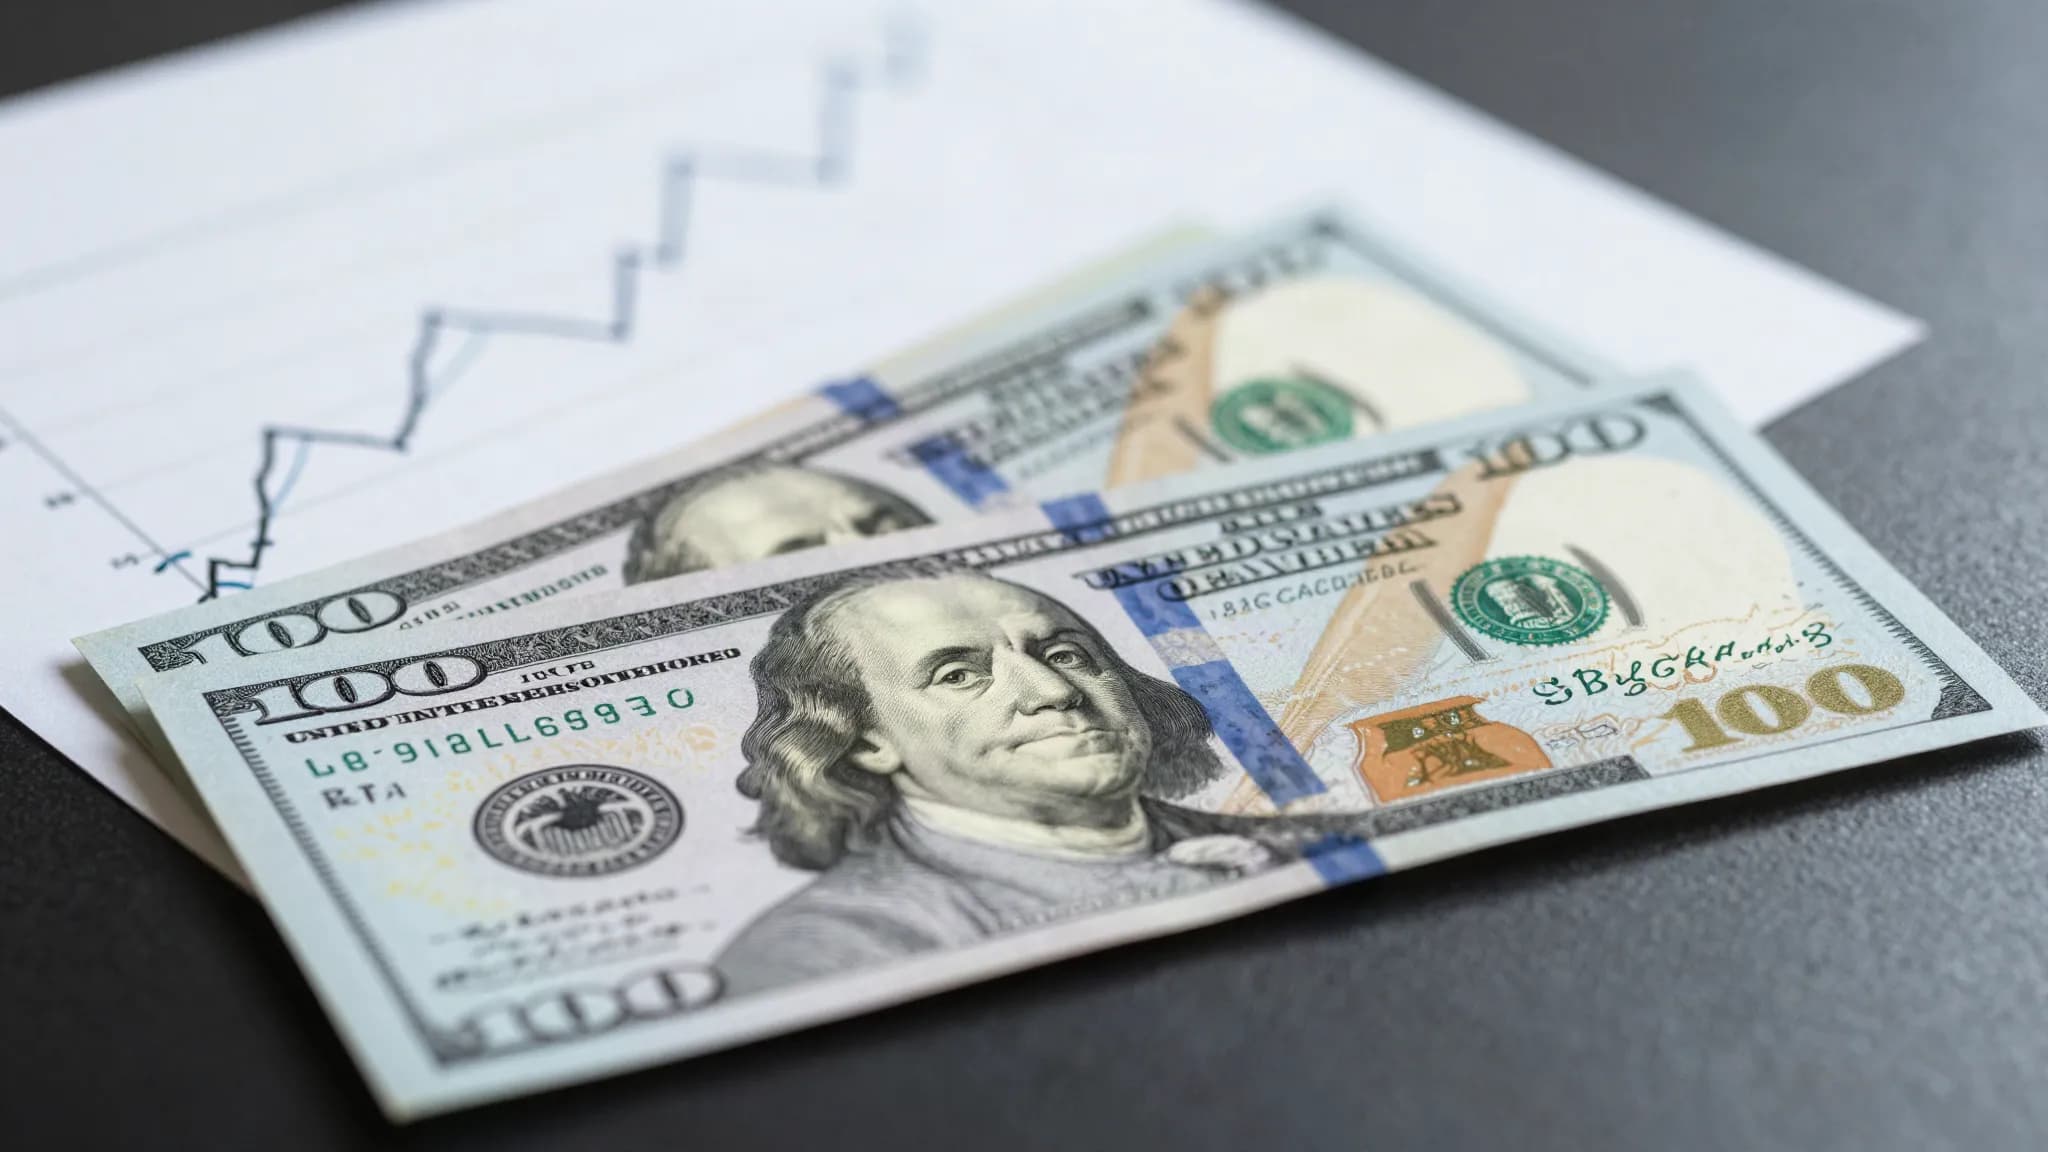
Currency markets are comparing two versions of the same problem. The United States has firm technology investment, stable employment and inflation above target. Europe is more exposed to the energy shock and is experiencing tighter private credit. Both central banks are cautious, but the reasons and economic costs differ.
What the latest evidence says
The Federal Reserve's July report described solid activity, a broadly stable labor market and strong productivity, while noting inflation had risen and remained above 2 percent. The ECB held its rates in July and warned that the full inflation effect of higher energy costs has yet to emerge. Its banks also expect credit standards to tighten further.
Federal Reserve July Monetary Policy Report provides the primary data and institutional assessment behind this report.
ECB July policy decision adds the second official reference used to compare the outlook and its risks.
Why this matters now
The dollar tends to benefit when US yields rise relative to peers or when investors seek liquidity during stress. Yet a currency cannot be forecast from rates alone. Growth expectations, fiscal borrowing, trade flows and positioning all matter. If US data soften while European energy conditions stabilize, the current policy contrast can narrow quickly.
What to expect in the upcoming period
August jobs and inflation releases will test whether the Fed can remain patient. In Europe, gas prices, bank lending and consumer confidence will show whether the ECB faces a longer stagflationary squeeze. A widening gap in expected policy paths would support a stronger directional move; synchronized caution may keep the pair rangebound.
The risk inside the forecast
Geopolitical headlines can overwhelm economic releases, especially when they affect energy routes. Intervention language and sudden changes in risk appetite also create reversals. Businesses should avoid turning a tactical currency view into an unhedged operating exposure.
What readers should watch next
For companies, scenario planning is more useful than guessing one year-end level. Test budgets under a stronger dollar, a European rebound and continued volatility. For investors, watch relative real yields and credit conditions together. The next sustained move will require one region's inflation-growth mix to become clearly more favorable than the other's.
Published in The Outspoken Digest
Newsletter
The Digest, in your inbox
One edition, sent when it is ready. No noise, and your address is never passed on.
Read Next
More Business →
Jio Platforms Raises Rs 8,110 Crore From Anchors at the Top of Its Range as India's Biggest IPO Opens
Oct 21, 2026/2 min read
Netflix Beats on Profit, Then Slides After Hours as It Trims Its Ad Forecast and Guides Lower
Oct 21, 2026/2 min read
Wall Street Rebounds as AI Stocks Recover, With the Nasdaq Up 1.1% and the 10-Year Yield Above 5.15%
Oct 20, 2026/2 min read

CoreWeave Shares Fall 25 Percent in a Week as Its Bonds Flash Warning Signs for AI's Borrowers
Oct 18, 2026/2 min read