The Senate Killed the Clarity Act by One Vote. Four Republicans Joined Every Democrat Over the President's Crypto
After 600 pages of compromise and hundreds of millions in lobbying, cloture failed 50 to 49, ten short. The sticking point was a clause to stop elected officials profiting from crypto while in office. The industry now has the SEC and the CFTC, and November.
Thursday, September 17, 2026/3 min read
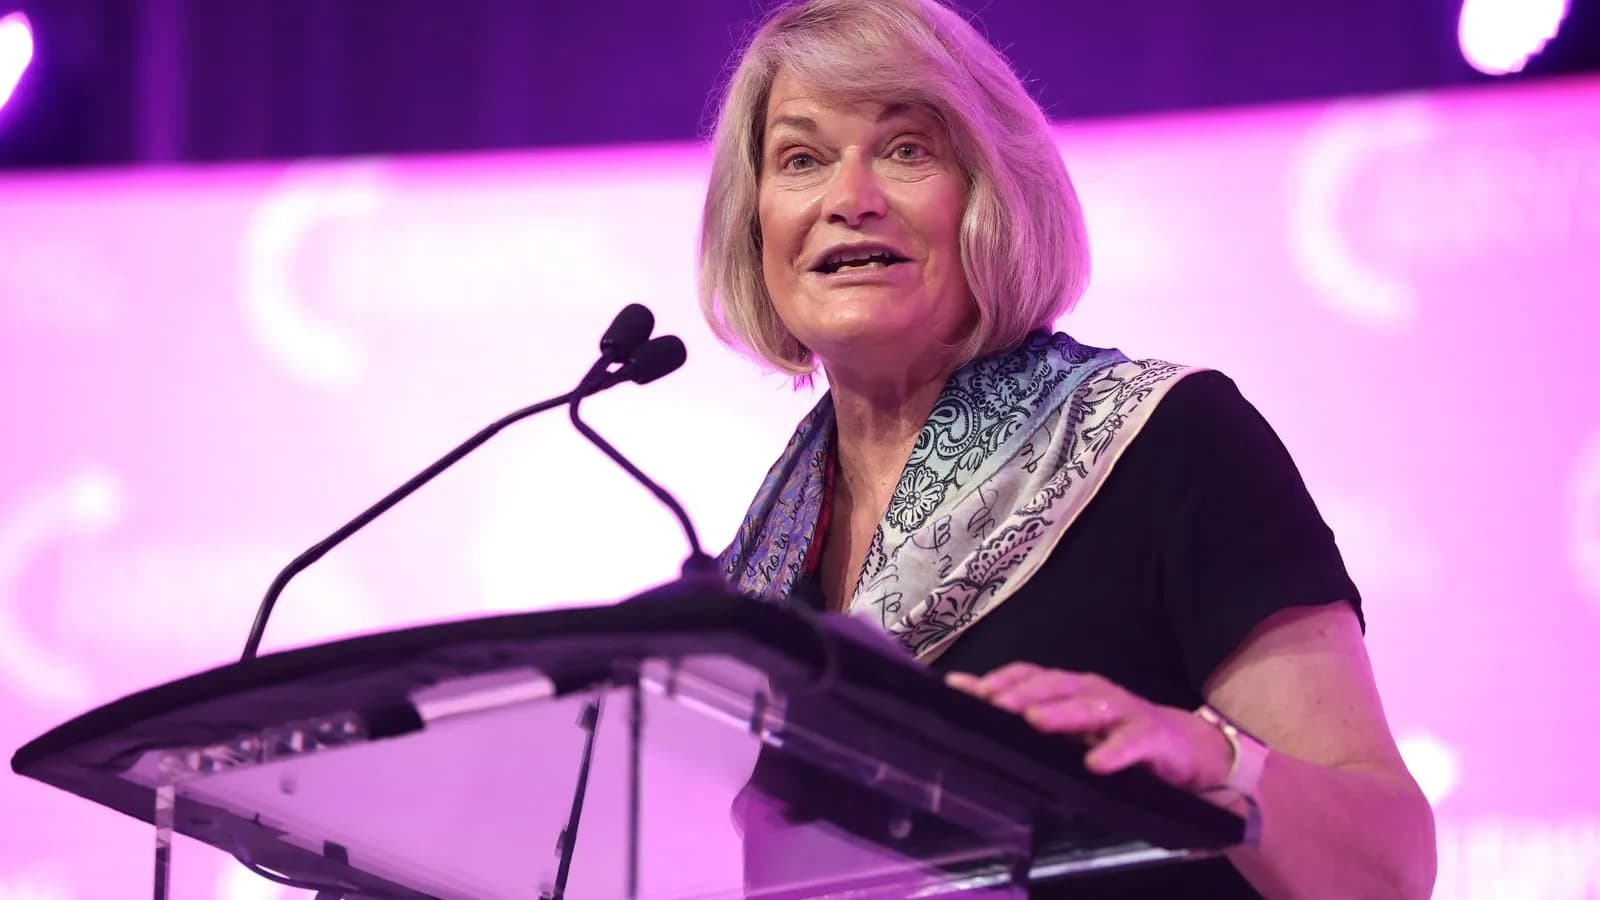
The Digital Asset Market Clarity Act needed sixty votes on Tuesday to open debate on the Senate floor and got fifty. The motion to invoke cloture failed 50 to 49. Every Democrat voted no, joined by four Republicans: Susan Collins of Maine, Josh Hawley of Missouri, Jerry Moran of Kansas and Thom Tillis of North Carolina. NPR called it a major defeat; CoinDesk, which is not a neutral observer, called it a flame-out. The industry had spent years and, by CoinDesk's count, hundreds of millions of dollars to get here, and had said in the days before the vote that it had the numbers. It did not have them by ten.
What the bill did
The act, which passed the House last year, would have drawn the line the industry has wanted since 2018: which digital assets are securities and belong to the Securities and Exchange Commission, which are commodities and belong to the Commodity Futures Trading Commission, with new CFTC authority over spot markets in the latter, registration regimes for exchanges and brokers, and stronger anti-money-laundering rules. More than 600 pages of compromise text had been negotiated, led on the Republican side by Cynthia Lummis of Wyoming. It would have completed the framework begun by the GENIUS Act on stablecoins, which passed in 2025 and remains the industry's only legislative win.
Why it failed
Not over any of that. The fight was over ethics language meant to stop the president, the vice president, members of Congress and senior officials from owning or profiting from crypto ventures while in office. Democrats wanted it to bite; the White House and most Republicans did not. Mark Warner of Virginia, a Democrat who has voted for crypto bills before, told the Wall Street Journal that the president's own ventures were "a fundamental conflict of interest" that the bill failed to address. The same week Bloomberg reported that Trump had made 28,700 stock trades in seventeen months, more than every member of Congress combined, and that he backs a bill exempting the presidency from trading rules. In that atmosphere, a clause about coins was never going to be waved through. Lummis's closing plea was the speech of someone who knew: "Do not let this day be the day we handed our future to someone else because we were too afraid to finish what we started."
What happens now
The session ends in December and a new Congress sits in January; Democrats need to gain only a handful of seats on 3 November to control at least one chamber, and CoinDesk's sources are already talking about investigations rather than legislation if they do. The realistic path for the next year runs through the agencies. The SEC has proposed Regulation Crypto Assets, its own attempt to define what it will and will not treat as a security, and the CFTC has been asserting spot-market authority piecemeal. Both can be reversed by a future commission in a way a statute cannot, which is the whole reason the industry wanted the statute. Its political committees, which spent heavily in 2024, are reviewing where the money goes before November.
The price
Bitcoin did not much care. It traded around 77,000 dollars through the vote, where it has sat since the oil shock, and the Fed's rate rise on Wednesday mattered more to it than the Senate did. That is the honest measure of the bill: it was about market structure, licensing and who regulates whom, and the traders who set the price had long since priced in a Washington that could not finish anything. The people who lose are the exchanges and brokers who wanted a rulebook, and the customers who would have had protections the SEC's enforcement docket does not provide. They will wait at least until the new year, and probably longer.
Published in The Outspoken Digest
Editorial desk
Outspoken Digest Markets DeskReports for The Outspoken Digest across Crypto, Business.
Newsletter
The Digest, in your inbox
One edition, sent when it is ready. No noise, and your address is never passed on.
Read Next
More Crypto →
Bitcoin Is Holding Near 77,000 Dollars as Rate Rise Odds Climb, Which Is Better Than the Textbook Says It Should
Sep 15, 2026/3 min read
Bitcoin Reclaimed 81,000 Dollars on a Rate Signal, Which Is Not What an Inflation Hedge Does
Sep 4, 2026/3 min read
The Exchange Has Built a Crypto Index That Deliberately Leaves Out Bitcoin and Ether
Sep 1, 2026/3 min read
An Attacker Minted Forty Nine Billion Dollars of SAND and Left With Six Hundred and Seventy Five Thousand
Aug 30, 2026/4 min read